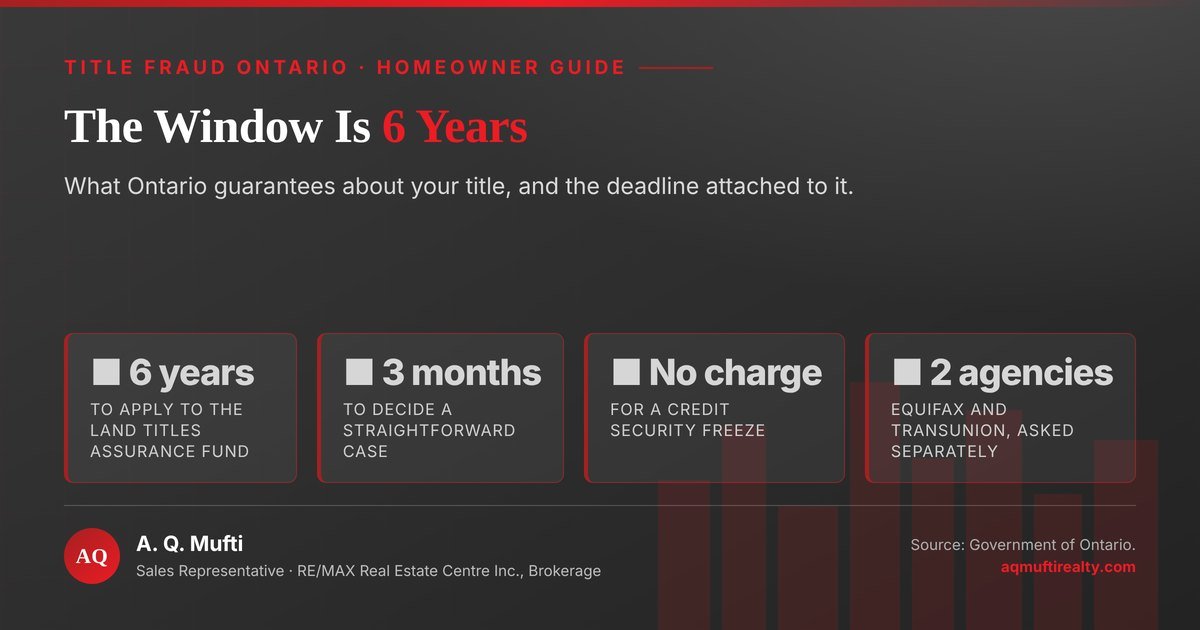
The four title fraud Ontario numbers worth knowing before you ever need them. Source: Government of Ontario.
Your house is probably the largest thing you own. The paperwork that says so is a line in a provincial register. Somebody who is not you can change that line.
Ontario does stand behind the register. That is the reassuring part. Yet the guarantee for title fraud Ontario owners is a claim with a clock on it, and that clock runs six years.
The short version
- The register is guaranteed, not unbreakable. A fraudster using a stolen identity can transfer your title and raise a mortgage on it.
- You have six years to apply. That is the window for a title fraud Ontario claim against the Land Titles Assurance Fund.
- A straightforward case takes about three months. The province says title can be returned and compensation decided in that time.
- A credit freeze costs nothing. Both Equifax and TransUnion must provide one, and you have to ask each separately.
- Title insurance is optional and portable in time. It is a one-time premium, and you can still buy it years after closing.
The title fraud Ontario numbers every owner should know
First the figures. Nearly every useful move a title fraud Ontario homeowner can make rests on one of them. Each row comes from the province or from its insurance regulator.
| What it measures | Figure | Source |
|---|---|---|
| Window to apply to the Land Titles Assurance Fund | 6 years from the loss | Government of Ontario |
| Typical time to return title and decide compensation | about 3 months | Government of Ontario |
| The same timeline, on the province’s other page | 90 days | Government of Ontario |
| Cost of a security freeze on your credit file | No charge | Government of Ontario |
| Credit agencies required to offer a freeze | 2, Equifax and TransUnion | Government of Ontario |
| Requests needed to freeze both files | 1 per agency | Government of Ontario |
| Freeze placed after an electronic request | within 2 business days | Government of Ontario |
| Freeze placed after a phone request | within 5 business days | Government of Ontario |
| Freeze placed after a mailed request | within 15 business days | Government of Ontario |
| Temporarily lifting a freeze becomes available | after July 1, 2027 | Government of Ontario |
| Title insurance required in Ontario | No | FSRA |
| Average GTA selling price, September 2026 | $1,006,409 | TRREB |
What title fraud Ontario homeowners actually face
Start with the mechanism. The word fraud covers several different crimes, and only one of them takes your house.
How a title fraud Ontario transfer happens
The province describes it plainly. Fraudsters use stolen identities or forged papers to move a registered owner’s title to themselves, the Government of Ontario explains, and the owner never hears of it.
Then comes the point of the exercise. They raise a mortgage on the home and vanish with the cash. A real lender is left holding a charge on a real house.
Why the register is the target
Ownership here is a record, not a document in your drawer. So the register is where an attack has to land. A forged signature there outranks the deed in your filing cabinet.
Equally, that is why the province backs it. A registry nobody could trust would be worse than none at all.
What this is not
Mortgage fraud, by contrast, usually hurts a lender. Fraudsters inflate a value through sales between collaborators. Identity theft is the tool, not the crime.
So the title fraud Ontario owners should guard against is narrower than the headlines suggest. Helpfully, that makes the defenses specific too.
Title fraud Ontario claims and the six-year clock
Next the remedy. Most homeowners have never heard of it, yet it has a name, a form and a deadline.
The fund behind your title
The province created the Land Titles Assurance Fund under the Land Titles Act. It pays for certain money losses from real estate fraud. It also covers errors in the land records themselves.
In other words, the guarantee is real. Even so, it is a fund you claim against, not a switch somebody flips. A Hearings Officer decides, and you must prove both the claim and the amount.
Title fraud Ontario claims run out after six years
Here is the deadline. You must apply “within six years from the time of having suffered a loss”, in the province’s own words.
Admittedly six years sounds generous. In practice a title fraud Ontario victim learns of it late, often from a lender’s letter. So the useful part of that window runs much shorter than it looks.
What the fund pays, and how fast
A title fraud Ontario claim can recover three things: the loss itself, reasonable legal costs tied to the claim, and other reasonable costs. Notably, no dollar cap appears on either provincial page.
For most simple cases the province says title can be returned and compensation decided “within three months”. Its other page on the same fund puts it at 90 days. That is the same period, counted differently.
The free step most title fraud Ontario owners skip
Now the cheapest item on this page. A fraudster needs credit in your name. Therefore making credit hard to open in your name is the title fraud Ontario defense that costs nothing.
The title fraud Ontario safeguard that is free
Ontario gives you the right to freeze your consumer file, and the province states that a freeze is free. You do not have to be a victim first.
A freeze limits who may see your file for the purposes that matter here. Those include opening new credit, raising existing credit, getting a mortgage and leasing a car.
Two agencies, and two separate requests
Ontario requires only Equifax and TransUnion to offer freezes. Crucially, a freeze at one does not freeze the other. So one phone call leaves half the job done.
The province also sets how fast they must act: two business days for an online request, five by phone, fifteen by mail. Ask online and the cover is live inside a week.
One catch worth planning around
Lifting a freeze for a short spell is a separate right. It only arrives after July 1, 2027. Until then a frozen file is not something you can switch off for an afternoon.
That matters if a mortgage sits anywhere in your plans. Freeze on purpose rather than on a whim. Talk to your lender and your lawyer about order before you apply.
Title insurance beside the title fraud Ontario fund
Then there is the private option. It covers more ground than the fund, and people often misread it.
Optional, and no substitute for advice
The regulator is blunt on the first point. “Title insurance is not a requirement in Ontario”, says FSRA, which regulates insurance in the province.
It is just as blunt on the second. A policy “does not replace legal advice when purchasing property”. Bear that in mind during any title fraud Ontario conversation, including this one.
What a title fraud Ontario policy covers
A title policy protects owners and their lenders. It covers unknown title defects, existing liens such as unpaid utilities, mortgages or taxes, encroachments, record errors and title fraud itself.
Equally, it leaves plenty out. Known defects, soil contamination and anything only a fresh survey would show all sit outside a standard policy. Read the exclusions before you lean on it.
You can still buy it after closing
Significantly, this is the detail that surprises people. Most owners buy the policy when they buy the home, FSRA says, “but it can also be purchased after the fact”.
So an owner who closed in 2014 and never gave it a thought has not missed out. The premium is a one-time payment, set by the home’s value and the insurer.
What to do first if title fraud Ontario hits your home
Finally, the order of operations. The province’s own advice opens with two words: act quickly.
- Call the police. Report it to your local service first. Almost everything that follows will ask for the report number.
- Call a real estate lawyer. Not a REALTOR, and not your insurance broker. This is a legal process, so it needs somebody who runs them.
- Reach the land registry office or the Director of Titles. The province lists the Director of Titles in Toronto at 416-314-4882.
- Tell your bank, then freeze your credit. Both agencies, separately. Ask for a copy of your file to read as well.
- Then start the title fraud Ontario claim. Inside six years, and ask your lawyer whether a policy you already hold should be claimed on too.
Why a REALTOR writes about title fraud Ontario at all
Because the asset is the point. Specifically, the average GTA home sold for $1,006,409 in September 2026, TRREB reported on October 6. An hour on a freeze and a policy is cheap cover on a number that size.
I am a sales representative, not a lawyer, and none of this is legal advice. Still, a homeowner should hear that the fund exists before they need it, not after.
Where I can help
I will walk the ownership side of this through with you. My home valuation shows what the asset is worth, the monthly market updates track the market around it, the guide for buyers covers what to ask your lawyer at closing, and my mortgage calculator helps if a freeze needs timing around financing.
Additionally, the Real Estate Council of Ontario publishes the rules your agent works under. Ten minutes, well spent.
Your questions on title fraud Ontario owners ask most
Short answers to what homeowners in Mississauga, Oakville and Milton ask me about protecting the title to a home.
How long do I have to claim for title fraud Ontario covers?
Six years from the time you suffered the loss, in the province’s words. Many owners find out late, though. Treat the day you learn of it as the start of a shorter practical window, and call a lawyer that week.
Does a credit freeze cost anything?
No. Ontario gives you the right to place one, and says it is free. Remember that Equifax and TransUnion take separate requests, because freezing one will not freeze the other. A title fraud Ontario attempt needs only one file left open.
Do I need insurance if the title fraud Ontario fund exists?
They cover different ground. The fund handles fraud and record errors after the event. A policy also covers liens, encroachments and record errors. FSRA says insurance is not required here, so ask a lawyer what suits you.
I bought years ago. Is it too late for a policy?
No. FSRA says most owners buy residential title insurance at purchase, but it can also be bought afterwards. The premium is a one-time payment, set by the home’s value and the insurer.
Will a freeze stop me getting a mortgage?
It can complicate the timing, which is the real catch. Lifting a freeze for a short spell only arrives after July 1, 2027. So plan the order with your lender and your lawyer before you apply.
Sources and further reading
- Victims of real estate fraud, from the Government of Ontario — what it is, and first steps
- Compensation for victims of real estate fraud, from the Government of Ontario — the six-year window
- The Land Titles Assurance Fund, from the Government of Ontario — how a claim is decided
- Credit reports and security freezes, from the Government of Ontario — the free safeguard
- Understanding title insurance, from FSRA — what a policy does
- September 2026 market release, from TRREB — the average price
- What a registrant owes you, from RECO — your protections
Keep reading on the blog
More guides and market analysis from this blog.
- The Buyer Representation Agreement in Ontario — what you sign
- Closing Costs in Ontario: A Buyer’s Guide — the lawyer’s bill
- The Principal Residence Exemption in Ontario — tax on a sale
- Fall Home Maintenance in the GTA — looking after the place
Ready to talk about protecting what you own?
Tell me your address and I will send you what the home is worth in the current market, along with the questions worth putting to your real estate lawyer about title. No pressure, and no obligation.
Prefer to start with a number? Get a tailored home valuation or run the figures in the mortgage calculator.
Disclaimer: This article draws on the Government of Ontario’s pages on real estate fraud, the Land Titles Assurance Fund and credit reports, on FSRA on title insurance, and on TRREB’s September 2026 release, all fetched on November 2, 2026. It offers information only. I am a sales representative, not a lawyer, and nothing here is legal, tax or financial advice. A suspected title fraud Ontario case belongs with a real estate lawyer and the police. Deadlines can change, so confirm them on the province’s pages. A. Q. Mufti – Sales Representative, RE/MAX Real Estate Centre Inc., Brokerage.
A. Q. Mufti — Sales Representative
RE/MAX Real Estate Centre Inc., Brokerage
MSc, PMP®, ABR®, SRS®, CNE®
416 908 5600 · 905 270 2000
info@aqmuftirealty.com
141-1140 Burnhamthorpe Rd. W., Mississauga ON L5C 4E9
Serving Mississauga, Oakville, Milton, Brampton, Toronto and the wider GTHA. More about how I work.