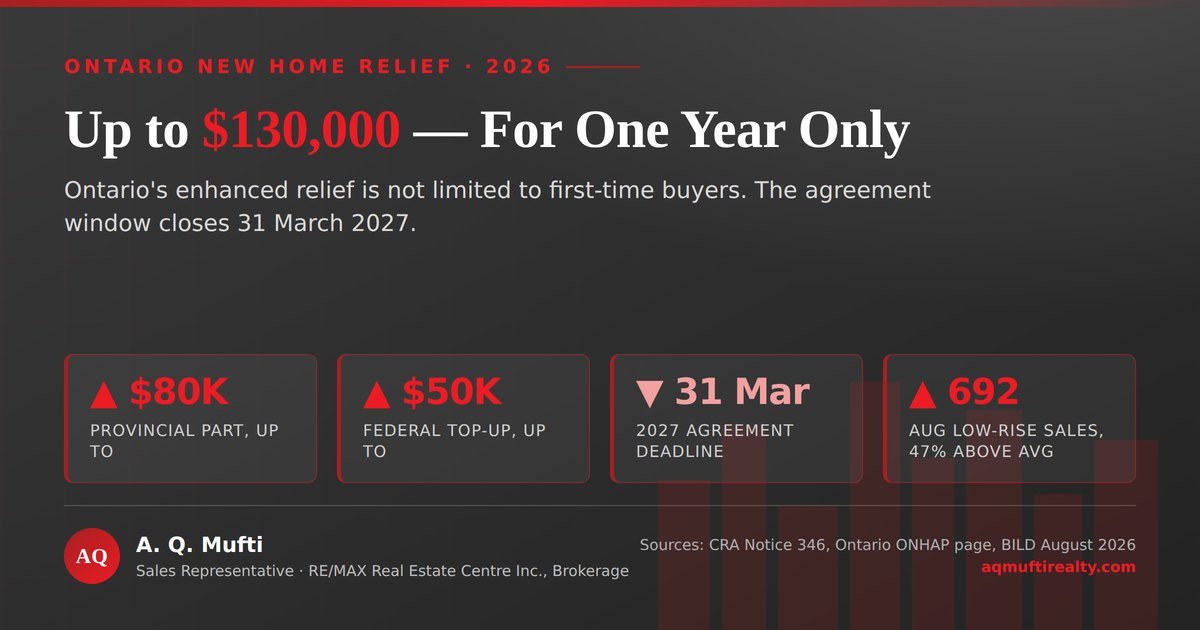
The new home HST rebate at a glance. Sources: Canada Revenue Agency Notice 346, the Ontario New Home Affordability Payment page and TRREB. Comparisons calculated.
There is more money on the table for a GTA buyer right now than at any point I can remember. Yet most people I speak to have the shape of it wrong. The new home HST rebate in Ontario is worth up to $130,000. It runs for a limited time, it covers new build only, and it carries no first-time buyer test.
However, that last point is the one that surprises people. The federal first-time buyer measure got the headlines in 2025, so buyers who already own assume none of this is for them. Yet Ontario’s own relief, layered on top in 2026, carries no such condition. What it carries instead is a deadline.
The short version
- Up to $130,000. The new home HST rebate covers the 8% provincial part of the HST, worth up to $80,000, plus a top-up on the 5% federal part worth up to $50,000.
- Anyone can claim it. The provincial measure has no first-time buyer test. The federal rebate does.
- A hard deadline applies. You have to sign the agreement of purchase and sale between 1 April 2026 and 31 March 2027.
- New build only. Resale falls outside all of it, so most GTA buyers gain nothing here at all.
- Above $1 million, the provincial route wins. On a benchmark new single-family home the difference is roughly $24,900 (calculated).
What the new home HST rebate pays, band by band
The bands below come from the Canada Revenue Agency’s notice on the Ontario measure and from the Ontario government’s own page. Both were current on the day I wrote this; still, programs change, so check the date on the page.
| Purchase price | Provincial part | Federal top-up | Combined |
|---|---|---|---|
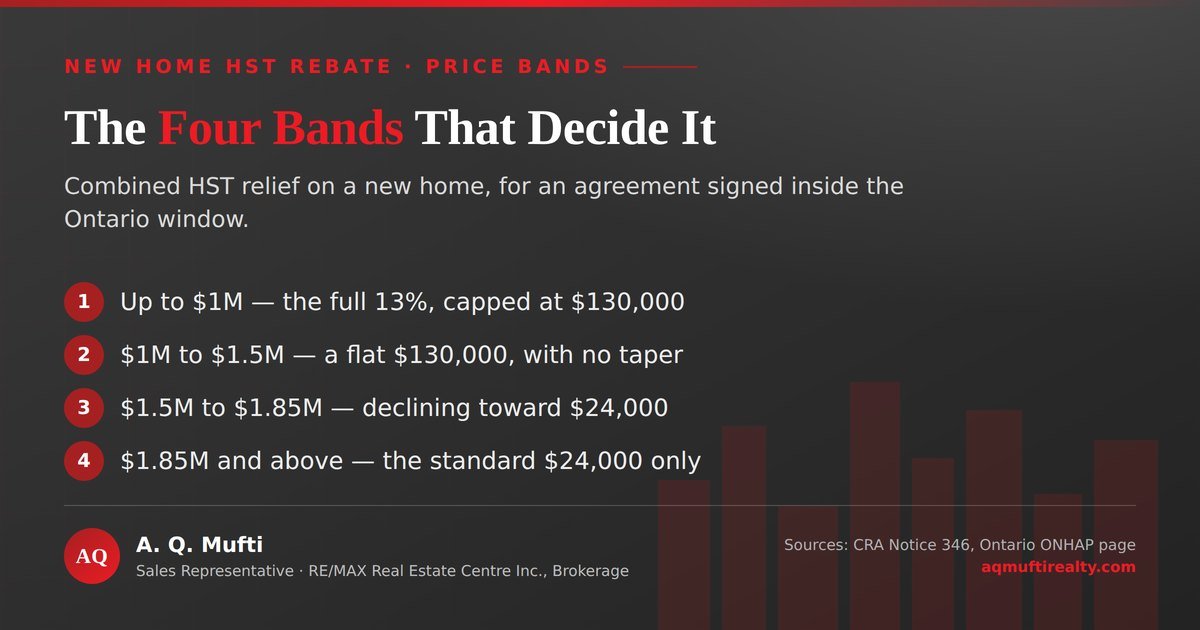
| Up to $1,000,000 | 100% of the 8%, max $80,000 | up to $50,000 | up to $130,000 |
| $1,000,000 to $1,500,000 | flat $80,000 | flat $50,000 | $130,000 |
| $1,500,000 to $1,850,000 | partial | partial | declining |
| $1,850,000 and above | standard rebate only | none | up to $24,000 |
What the new home HST rebate is actually made of
In short, the new home HST rebate is two separate things wearing one name. Indeed, knowing which is which saves a lot of confusion at the lawyer’s office.
The first piece is the Ontario enhanced new housing rebate. In short, it returns 100% of the 8% provincial part of the HST, up to $80,000, on a new or substantially renovated home. Between $1 million and $1.5 million it becomes a flat $80,000 rather than tapering away.
The second piece is the Ontario New Home Affordability Payment. Also, Ontario describes it as top-up relief of up to $50,000, equivalent to the 5% federal portion. You have to qualify for the first piece before you can receive the second.
Add them and the headline figure appears. So the combined figure is really one provincial rebate and one provincial top-up, rather than a federal program at all.
The new home HST rebate is not only for first-time buyers
Most of the confusion about the new home HST rebate sits here. Being precise pays, because the two programs behave differently above $1 million.
The federal first-time home buyers’ rebate returns up to $50,000 of the GST and tapers between $1 million and $1.5 million. At $1.25 million the Canada Revenue Agency’s own example gives half the maximum, or $25,000. Above $1.5 million it disappears.
By contrast, Ontario’s top-up does not taper in that band. Instead, it stays flat at $50,000 all the way to $1.5 million. Consequently, for a home priced above $1 million, the provincial route is simply worth more than the federal one.
A worked comparison at benchmark prices
Take the benchmark price of a new single-family home in the GTA, $1,248,866. At that price the federal first-time buyer rebate comes to about $25,100. Ontario’s top-up pays the flat $50,000 instead. That gap runs to roughly $24,900, and I calculated both figures from the published bands.
| At a $1,248,866 new home | Federal first-time rebate | Ontario top-up |
|---|---|---|
| Amount on the 5% part | about $25,100 (calculated) | $50,000 |
| First-time buyer required | yes | no |
| Agreement window | 20 Mar 2025 to end of 2030 | 1 Apr 2026 to 31 Mar 2027 |
| Can be combined with the other | no | no |
Notably, they do not add together. Ontario states plainly that it reduces its payment by the federal portion of any HST rebate you claim, the first-time buyer rebate included. Therefore a first-time buyer inside the Ontario window gains nothing extra from that status. So for one year, the new home HST rebate has quietly made the distinction worth very little.
The dates that decide the new home HST rebate
Every part of the new home HST rebate turns on paperwork dates rather than closing dates. That is why it catches people out.
For the Ontario measure, you have to sign with the builder between 1 April 2026 and 31 March 2027. Building has to start by the end of 2028 and finish by the end of 2031. Sign in April 2027 and the relief does not apply, however new the home.
The federal first-time buyer rebate runs on a longer clock. The Canada Revenue Agency requires an agreement on or after 20 March 2025 and before 2031. Also, the build has to finish before 2036. You must be the first person to live in it, too.
Who the new home HST rebate leaves out
Resale buyers, entirely. None of this touches a home someone has already lived in, because there is no HST on that sale to rebate in the first place.
In fact, that exclusion is larger than it sounds. For example, the Toronto Regional Real Estate Board recorded 5,057 resale transactions across the GTA in August, against 907 new home sales. So fewer than one buyer in six was even in the room for this (calculated).
What GTA buyers did with the new home HST rebate
August figures from the Building Industry and Land Development Association show a market splitting in two. The split follows this relief almost exactly. Indeed, the pattern is hard to miss.
Specifically, single-family new home sales reached 692 units, which is 47% above the ten-year average for August. Meanwhile, new condominium apartments managed 215 units, which is 78% below their ten-year average. Total sales were 907.
Edward Jegg, research manager at Altus Group, said GTA new home sales in August “continued to be buoyed by single-family sales that are benefitting from the HST rebate”. Justin Sherwood, chief operating officer at BILD, put it more directly: after five straight months of rising low-rise sales, “it is clear that the HST rebate program in Ontario is working”.
Why condominiums are missing out
Sherwood also noted that condominiums “are continuing to struggle to benefit from the rebate program”. The reason is structural rather than financial. A tower signed today does not start building quickly, and the deadlines here suit houses far better than towers.
Meanwhile inventory tells its own story. There were 19,030 unsold new homes across the region, or 38.5 months of supply, and 12,734 of those were condominium apartments. So buyers have leverage there that they do not have on a low-rise lot.
Finally, one more wrinkle is worth knowing. The benchmark new condo apartment price is $1,041,918, just over the line where the federal first-time rebate starts to taper. The Ontario flat band covers it in full, which is another reason to check both routes before signing.
How to check the new home HST rebate on a real purchase
Generally, averages orient you. Still, a signature needs the real figures for the real agreement, and five checks on the new home HST rebate do most of the work.
- Find the date on the agreement. Not the closing date, not the occupancy date. The rule reads the day you signed the agreement of purchase and sale.
- Ask whether the builder credits it at closing. Many builders apply the relief against the purchase price and claim it themselves, which changes what you need to finance.
- Check the price against the bands. Below $1 million, between $1 million and $1.5 million, and above $1.5 million are three different outcomes.
- Run the payment on the net figure. Work out the monthly cost on what you actually finance using the payment calculator, not on the sticker price.
- Confirm the construction timetable in writing. The relief depends on when building starts and finishes, and those dates belong to the builder rather than to you.
If all five hold, the relief is real money and it should change what you are willing to pay. If any one of them fails, treat the new home HST rebate as worth nothing and price the home on its merits instead.
New to the process? My step-by-step guide for buyers covers the sequence from pre-approval to keys, and the home finder will flag matching properties as they list.
Your questions about the new home HST rebate
Short answers to what buyers are asking me this month.
Do I have to be a first-time buyer for the new home HST rebate?
No, not for the Ontario part. The enhanced new housing rebate and the New Home Affordability Payment have no first-time buyer test. By contrast, only the separate federal rebate does.
Can I claim the federal rebate and the Ontario top-up together?
No. Ontario reduces its payment by the federal portion of any HST rebate you claim, including the first-time buyer rebate. Therefore you get one amount on the 5%, not two.
Does any of this apply to a resale house?
No. It covers new or substantially renovated homes only. A resale home does not attract HST on the sale price, so there is nothing to rebate.
What happens if I sign after 31 March 2027?
Then the Ontario relief does not apply. A first-time buyer may still qualify for the federal rebate, which runs to the end of 2030, but the flat $50,000 band disappears.
Is a pre-construction condo covered?
It can be, provided the agreement falls inside the window and the building meets the construction deadlines. Those deadlines are the sticking point for towers, which is why condo sales have not responded the way houses have.
Sources and further reading
- Canada Revenue Agency – Ontario enhanced new housing rebate — bands, maximums and the agreement window
- Canada Revenue Agency – Notice 346 — the full notice on the Ontario measure
- Government of Ontario – New Home Affordability Payment — the top-up on the federal part, updated 17 September 2026
- Canada Revenue Agency – first-time home buyers’ rebate — who can apply, and the qualifying dates
- TRREB – HST rebate on a new home — the combined $130,000 figure explained
- BILD – GTA new home sales, August 2026 — released 22 September 2026, Altus Group data
- TRREB – Market Watch, August 2026 — 5,057 resale transactions across the GTA
Keep reading on the blog
More market analysis and practical guides from this blog.
- Closing Costs in Ontario, Itemized — everything else you pay on closing day
- GTA Real Estate Fall 2026: What Buyers Must Do Now — the wider market backdrop
- GTA Home Prices: August 2026 — where resale prices actually sit
- GTA Condo Rental Yield: The Truth About Easy Money — if you are buying the unit to rent it out
Ready to talk about your next move?
Bring me the builder’s agreement and I will read the dates with you before you sign, not after. We can work out what the relief is really worth on that specific home, and whether the price still makes sense without it. No pressure, and no obligation.
Prefer to start with a number? Get a tailored home valuation or run the figures in the mortgage calculator.
Disclaimer: This article draws on Canada Revenue Agency publications, Government of Ontario guidance, TRREB and BILD data, and it offers information only. Also, I calculated the comparisons between the two rebates from the published bands. Tax relief depends on facts specific to your agreement, so confirm your own position with your lawyer or an accountant. Nothing here is financial, mortgage, tax or legal advice, and programs change. A. Q. Mufti is a registered Sales Representative with RE/MAX Real Estate Centre Inc., Brokerage, Ontario, Canada.
A. Q. Mufti — Sales Representative
RE/MAX Real Estate Centre Inc., Brokerage
MSc, PMP®, ABR®, SRS®, CNE®
416 908 5600 · 905 270 2000
info@aqmuftirealty.com
141-1140 Burnhamthorpe Rd. W., Mississauga ON L5C 4E9
Serving Mississauga, Oakville, Milton, Brampton, Toronto and the wider GTHA. More about how I work.