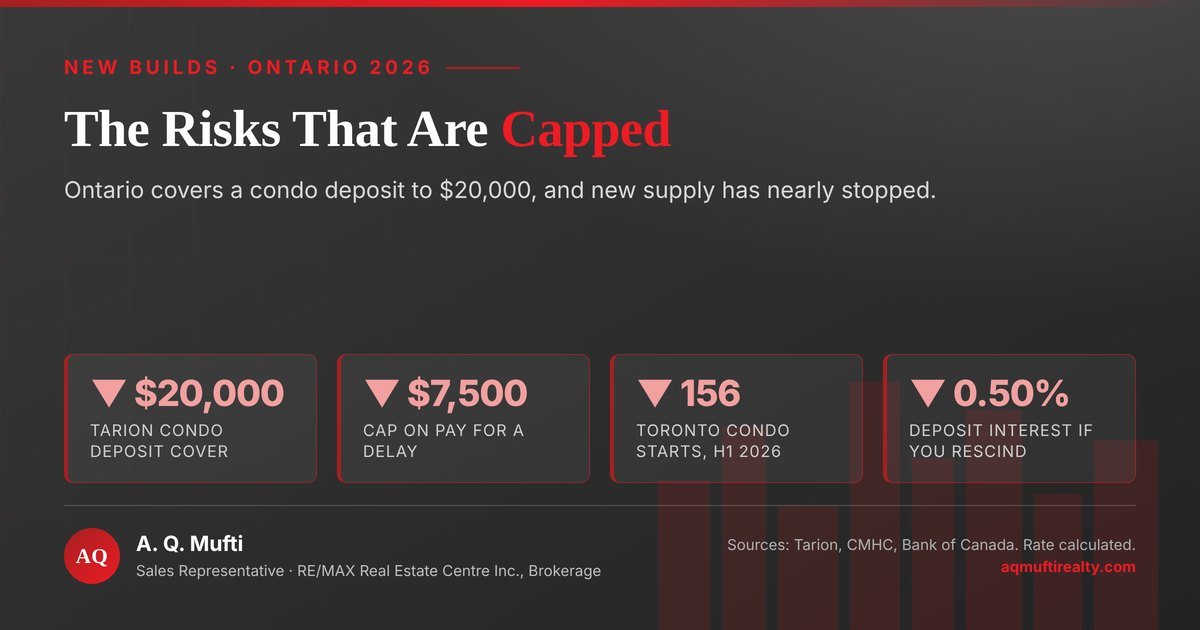
The capped risks in a new condo purchase, at a glance. Sources: Tarion, the Condo Authority of Ontario, CMHC and the Bank of Canada. Rate calculated.
A floor plan and a set price feel safer than a bidding war. Yet a new condo purchase hides costs that a resale deal does not.
Still, Ontario caps several of the protections. Notably, a condo deposit is covered to $20,000, however large that deposit is.
The short version
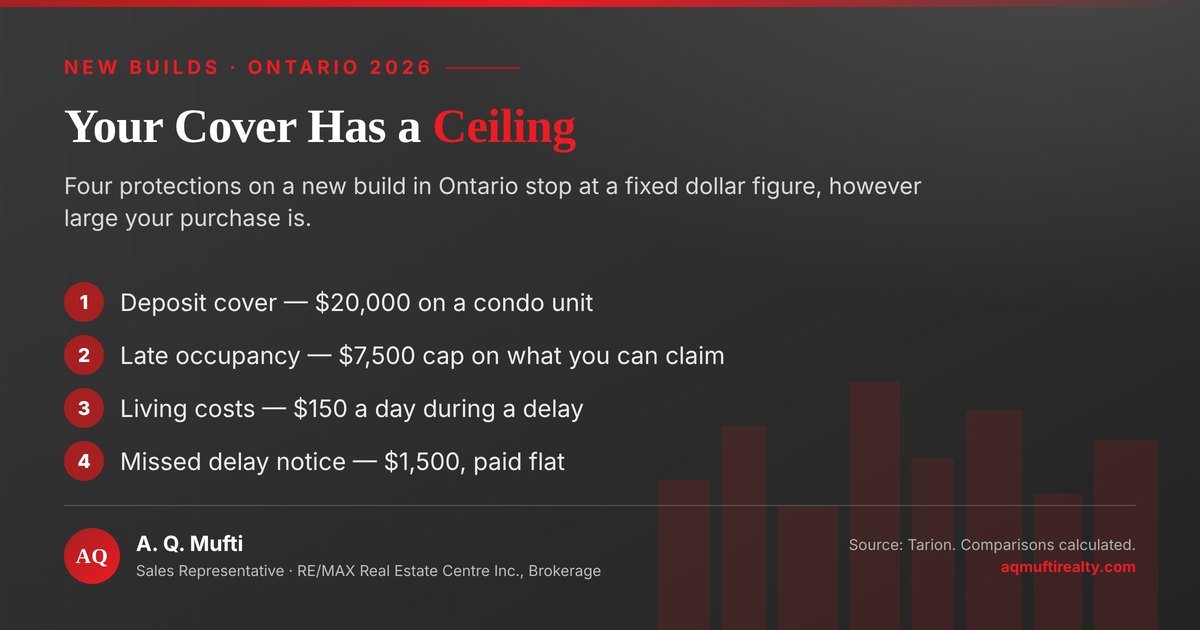
- Deposit cover stops at $20,000. Tarion insures a condo deposit to that cap. A freehold home can be covered to $100,000.
- Pay for a delay is capped too. In short, it tops out at $7,500, built from $150 a day in living costs.
- You pay to live in a home you do not own. Typically interim occupancy fees start at move-in. Meanwhile no mortgage payment begins, so a new condo purchase builds no equity yet.
- Your deposit earns almost nothing. In fact the rate is two points below the Bank Rate, or 0.50% today (calculated).
- Supply has thinned sharply. Just 156 condo units started in the City of Toronto in the first half of 2026, against about 7,000 a year in the past decade.
A new condo purchase in numbers
First, here are the parts of a new condo purchase that carry a legal ceiling. You can price these exactly, because Ontario has written the number down.
| Protection or measure | Condo unit | Source |
|---|---|---|
| Deposit cover | $20,000 | Tarion |
| Freehold deposit cover | up to $100,000 | Tarion |
| Pay for a late occupancy date | $7,500 cap | Tarion |
| Living costs during a delay | $150 a day | Tarion |
| Missed delay notice | $1,500 flat | Tarion |
| Cooling-off period | 10 days | Condo Authority |
| Deposit interest if you rescind | 0.50% today | calculated |
What a new condo purchase looks like in 2026
Start with supply. Indeed it has changed far more than any clause in a builder’s contract.
A market that nearly stopped building
CMHC counted just 156 condo units starting work in the City of Toronto in the first half of 2026. Over the past decade the city averaged about 7,000 a year.
The mix has flipped too. Meanwhile, across the wider Toronto area, rental starts hit 12,062 against 8,289 condo starts. Rental has not led since 1994.
So a new condo purchase in 2026 is not the deal it was in 2019. Builders launch fewer towers now. The stock of permitted units waiting to start has also fallen 50% from its 2023 peak.
What thin supply does to the risk
Clearly, fewer launches cut both ways. You get less choice, yet you also face less new stock competing with your unit later.
Still, CMHC puts the real worry plainly. The bigger long-term risk, it writes, “may not be excessive rental construction,” but too little for sale, in its Fall 2026 supply report.
The deposit is where a new condo purchase is least protected
Next, look at the cash. First, it leaves your account on signing. Then it sits with the builder for years.
Why $20,000 is the number that matters
Notably, Tarion states its limit plainly. It “provides deposit protection of up to $20,000 plus a limited amount of interest that has accrued” on a condo unit, in its coverage summary.
Now compare a freehold home. Specifically, cover there runs to $60,000 on a price of $600,000 or less. Above that it is 10% of the price, to a cap of $100,000.
So the gap is the real risk in a new condo purchase. A 20% deposit on the September 2026 GTA average of $1,006,409 comes to $201,282, and Tarion covers about a tenth of it (both calculated).
The interest nobody mentions
Deposits are held in trust and do earn interest. But the Condominium Act sets that rate at two points below the Bank Rate, as the Condo Authority explains.
The Bank held its policy rate at 2.25% on September 2, 2026, “with the Bank Rate at 2.5%,” it said that day. So a deposit you get back earns 0.50% today (calculated).
Interim occupancy, the new condo purchase cost nobody budgets
Now think about the gap between moving in and owning. In practice it has a name, interim occupancy. It also has a bill.
Paying to live in a home you do not own
In this phase you live in the unit but hold no title. Here the Condo Authority is blunt about the fee. You owe it “whether or not they move in.”
The fee has three parts. It cannot exceed the total of monthly interest on the unpaid price at the set rate, the estimated monthly city taxes, and the projected common expense fees.
What it costs, and what it does not buy
Still, none of it pays down a mortgage. Those payments cannot start until the condo corporation is registered at the Land Registry Office. Hence the fee builds no equity at all.
Put simply, size it before you sign. On an unpaid balance of $560,000, each half point of interest is about $233 a month (calculated). That is why interest drives the cost of a new condo purchase in this phase.
Delays and cancellations in a new condo purchase
Next comes the new condo purchase risk buyers hear about most and measure least. Typically, dates move. Now and then a project dies.
The two dates that bind the builder
First, two dates sit in the Statement of Critical Dates. The Firm Occupancy Date is the agreed finish date. The Outside Occupancy Date is the builder’s fallback if the firm date slips.
Yet missing the outside date gives you an exit. A buyer may cancel within 30 days. Also, 90 days of written notice is the general rule for moving a closing date.
What a delay is worth in cash
Again, Tarion sets those figures. Pay runs “up to a maximum of $7,500,” living costs are met at “a fixed amount of $150 a day for each day of delay,” and a builder who misses the ten-day delay notice owes a flat $1,500, per its condo coverage page.
By contrast, a dead project is the harder case. Tarion says it “does not have authority to compel a vendor to complete a condominium project that they decide to cancel.” Complaints go to the Home Construction Regulatory Authority.
Why leaving a new condo purchase is hard
Generally, buyers assume they can just walk away from a deal that sours. In truth two narrow doors exist, and a third has grown costly.
Ten days, then a material change
First, Ontario gives you a 10-day cooling-off period. You may also rescind later if there is a material change to the facts in the disclosure statement.
After that, the deal binds you. Note too that it is not binding at all until you have both the disclosure statement and Ontario’s Residential Condominium Buyers’ Guide.
The assignment door, and its tax
Assignment used to be the quiet exit from a new condo purchase. But the CRA now treats it as a sale: “Effective May 7, 2022, all assignment sales in respect of newly constructed or substantially renovated residential housing are taxable for GST/HST purposes,” per its assignment info sheet.
One carve-out survives, and it has a condition. The CRA’s notice on the change would “exclude any amount attributable to a deposit paid by an assignor to a builder.” Yet it applies only where the deal “indicates in writing” that part of the price repays that deposit.
So the wording decides the bill. Assign for $180,000 after paying $140,000 in deposits and the tax at 13% is $5,200 on the $40,000 gain, or $23,400 on the whole sum without that clause (calculated).
How to price a new condo purchase against resale
Of course, none of this argues against buying new. It argues for costing the years between signing and owning.
If you plan to live there
- Budget the occupancy phase, not just the closing. Ask for the projected fee in writing. Then run the rest through my payment calculator.
- Read the Critical Dates before the floor plan. Those two dates set your real timeline, and the addendum wins if the contract disagrees.
- Use all ten days. Give your lawyer the disclosure statement on day one, since the clock will not pause for a busy week.
- Compare with resale honestly. In fact a like-for-like GTA home is worth 4.7% less than a year ago on the index. So a 2029 price deserves a hard look.
If you plan to rent it out
- Treat assignment as taxable, not as an exit. Price the tax in. Then have the deposit clause drafted before you need it.
- Stress-test the registration date. Carrying costs in the occupancy phase are real, and they earn you nothing.
- Check what else is launching nearby. With starts this thin, the risk in a new condo purchase shifts toward delay rather than a glut.
Equally, one policy shift cuts the other way. Development charges “can account for up to 20 per cent of a home’s purchase price,” and Ontario has funded a 40% to 60% cut in Toronto with $1.5 billion, TRREB reported.
Want the whole sequence in writing? For instance, my step-by-step guide for buyers runs from pre-approval to keys. The monthly market updates track the resale figures above as they move.
Your new condo purchase questions
Short answers to what buyers and investors ask me most about buying new.
What is the biggest risk in a new condo purchase?
Capped cover and uncosted time. Tarion insures a condo deposit to $20,000 and pay for a delay to $7,500. Meanwhile occupancy fees run for months and build no equity.
Can I get my deposit back if a project is canceled?
Usually yes, with interest, since deposits in a new condo purchase are held in trust. But if it is not repaid, a Tarion claim covers only $20,000 of a condo deposit.
How long is the cooling-off period on a new condo purchase?
Ten days. You may also rescind later if there is a material change to the disclosure statement. So give your lawyer the documents at once.
Do I pay a mortgage during interim occupancy?
No. Mortgage payments cannot start until the condo corporation is registered. Instead you pay a fee covering interest, estimated taxes and projected common expenses.
Is assigning my unit still a cheap way out?
Rarely. Generally the CRA says all assignment sales of new housing are taxable. The deposit is left out only where the deal says so in writing.
Sources and further reading
- Condo Authority – new builds — the rules
- Tarion – deposit cover — $20,000
- Tarion – condo delays — $7,500
- CMHC – Fall 2026 — 156 starts
- CRA – assignments — the tax
- CRA – notice 323 — the carve-out
- Bank of Canada – September — 2.5%
- TRREB – September 2026 — resale
- TRREB – charges — the cut
Keep reading on the blog
More guides and market analysis from this blog.
- GTA Condo Rental Yield — the math
- New Home HST Rebate in Ontario — the rebate
- Closing Costs in Ontario — the extras
- GTA Home Sales, September 2026 — resale now
Ready to weigh a new condo purchase with me?
Send me the project and the floor plan you are considering and I will put its occupancy terms, deposit schedule and critical dates beside comparable resale listings in the same area. No pressure, and no obligation.
Prefer to start with a number? Get a tailored home valuation or run the figures in the mortgage calculator.
Disclaimer: This article draws on the Condo Authority of Ontario, Tarion, CMHC’s Fall 2026 Housing Supply Report, the Canada Revenue Agency, the Bank of Canada and TRREB. It offers information only. I calculated the 0.50% deposit rate, the two worked examples and the share of a deposit Tarion covers. Caps and market figures change, so review every document with a lawyer before you sign. Nothing here is financial, mortgage, tax or legal advice. A. Q. Mufti – Sales Representative, RE/MAX Real Estate Centre Inc., Brokerage.
A. Q. Mufti — Sales Representative
RE/MAX Real Estate Centre Inc., Brokerage
MSc, PMP®, ABR®, SRS®, CNE®
416 908 5600 · 905 270 2000
info@aqmuftirealty.com
141-1140 Burnhamthorpe Rd. W., Mississauga ON L5C 4E9
Serving Mississauga, Oakville, Milton, Brampton, Toronto and the wider GTHA. More about how I work.