
Anticipated interest rate cuts are changing the outlook for Canadian borrowers. Recent forecasts show a significant shift in what economists expect from the Bank of Canada (BoC). Many now see cuts arriving earlier than they first thought. As a result, financial forecasts are being revised, especially for the mortgage market.
This post was first written in November 2023. The forecasts below are from that time.
How Forecasts for Interest Rate Cuts Shifted
Previously, economists expected the BoC to wait until September to cut rates. Then a key October jobs report came out on November 3. It pointed to weakness in the labour market, a sign that inflation pressures could ease. You can find these monthly jobs figures at Statistics Canada.
That report, along with other economic signs, changed the timeline. Most analysts now expect BoC rate cuts as early as July 2024. Some even expect them to begin in April.
What the Forecasts Mean for Mortgage Rates
Mortgage rate forecasts point downward, which is a relief for borrowers. The average rate for five-year variable mortgages is projected to fall from the current 5.8 percent to 5.4 percent by the end of next year. Similarly, three-year fixed-rate mortgages are expected to drop from 5.7 percent to 5.2 percent by 2024.
If interest rate cuts arrive as forecast, monthly payments would ease a little. For a buyer, even a small drop can change how much home fits the budget.
Interest Rate Cuts in Context
Despite these hopeful projections, it is crucial to keep some perspective. The expected rates are lower, but they are still above pre-pandemic levels. The shift marks an easing after the rapid rate increases since March 2022. Yet it also suggests that rates will stay above average for some time.
In other words, cheap money is not coming back soon. So plan your purchase around today’s numbers, not the very low rates of the past.
This matters for sellers too. Some buyers may wait on the sidelines for lower rates. Others will act now to beat the spring crowd. Therefore, a home that is priced well and shows well can still sell, even while rates stay high. Meanwhile, buyers who are ready to move may find less competition than they will once rates fall.
The Bank of Canada’s Fight Against Inflation
Labour shortages and wage growth have both eased lately. That has given the BoC more confidence that inflation is coming down. It also fits with the Bank’s recent pauses, which reflect a careful plan to watch inflation cool before it acts.
For more on how the Bank weighed its choices then, read my post on the October 2023 rate decision. Until interest rate cuts begin, the Bank’s message is patience.
Mortgage Renewals: The Challenge Ahead
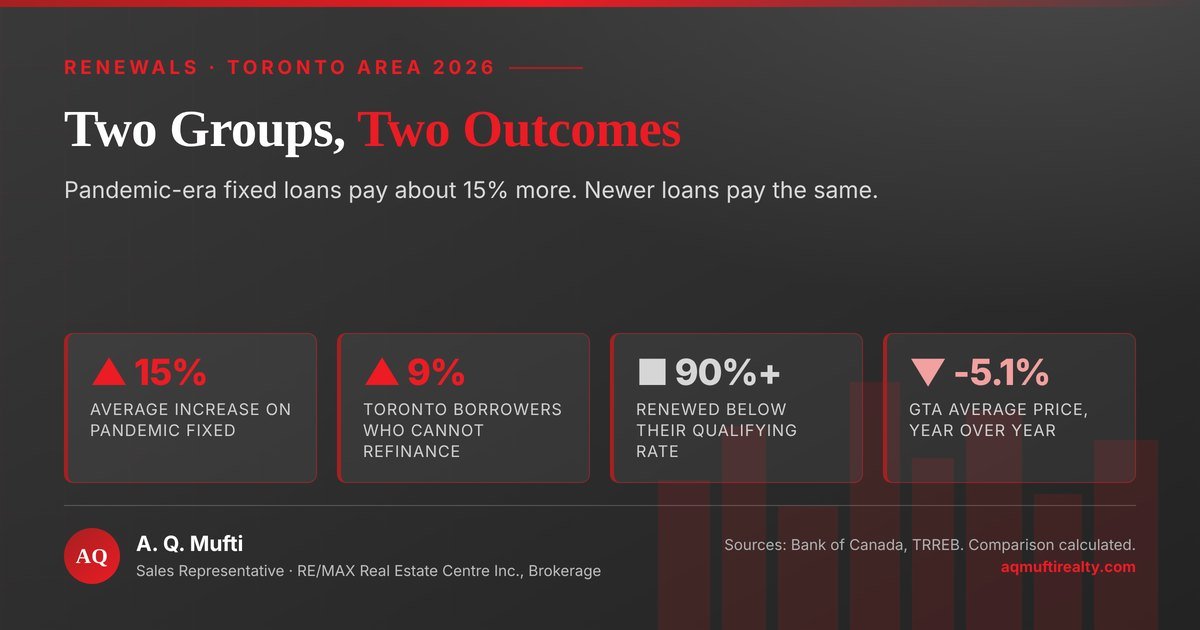
A big challenge looms. About $900 billion worth of Canadian mortgages will renew from 2024 to 2026. At current policy rates, those renewals could bring a serious “payment shock” for borrowers, with large jumps in monthly payments.
For many owners in Mississauga and the GTA, that renewal date is the real deadline. So interest rate cuts, or the lack of them, will shape family budgets for years.
How Canadians Are Preparing
In anticipation of these challenges, Canadians have changed their spending habits. Meanwhile, banks have worked with borrowers to soften the blow by offering relief measures.
If your renewal is coming up, start early. Here are a few steps to take:
- Find out your renewal date and your current rate.
- Talk to your lender at least a few months before renewal.
- Compare offers from other lenders as well.
- Ask about options such as a different term or amortization.
For a closer look at falling rates, read my post on the five-year fixed rates falling below 5%. Also, interest rate cuts are only one part of your plan, so keep an eye on your own budget.
Interest Rate Cuts: A Transitional Phase
The expected cuts offer a glimmer of relief for borrowers. However, they are only one step on a longer road back to normal rates. To borrow the words of Winston Churchill, this is not the end of high interest rates, but perhaps the end of the beginning. A new and nuanced financial landscape is yet to unfold.
Talk to a Mississauga real estate agent
Do you have questions about interest rates, renewals or buying a home? I am happy to help. Call A. Q. Mufti, Sales Representative, RE/MAX Real Estate Centre Inc., Brokerage, at 416 908 5600, or send me a message. And if this post helped you, a Google Review is always appreciated.
Disclaimer: this article was published on 18 January 2025 and reflects the information available at that time. Interest rates, prices, and government programs change, so check the current position before acting on anything here. It is provided for information only and is not financial, mortgage, tax or legal advice. A. Q. Mufti is a registered Sales Representative with RE/MAX Real Estate Centre Inc., Brokerage, Ontario, Canada.